
By Robin WenData as of
Silicon Carbide Manufacturers: Two Forms
Silicon carbide manufacturers and suppliers split into two chains: abrasive grit sold by the tonne, and substrates sold by the wafer.
On this page
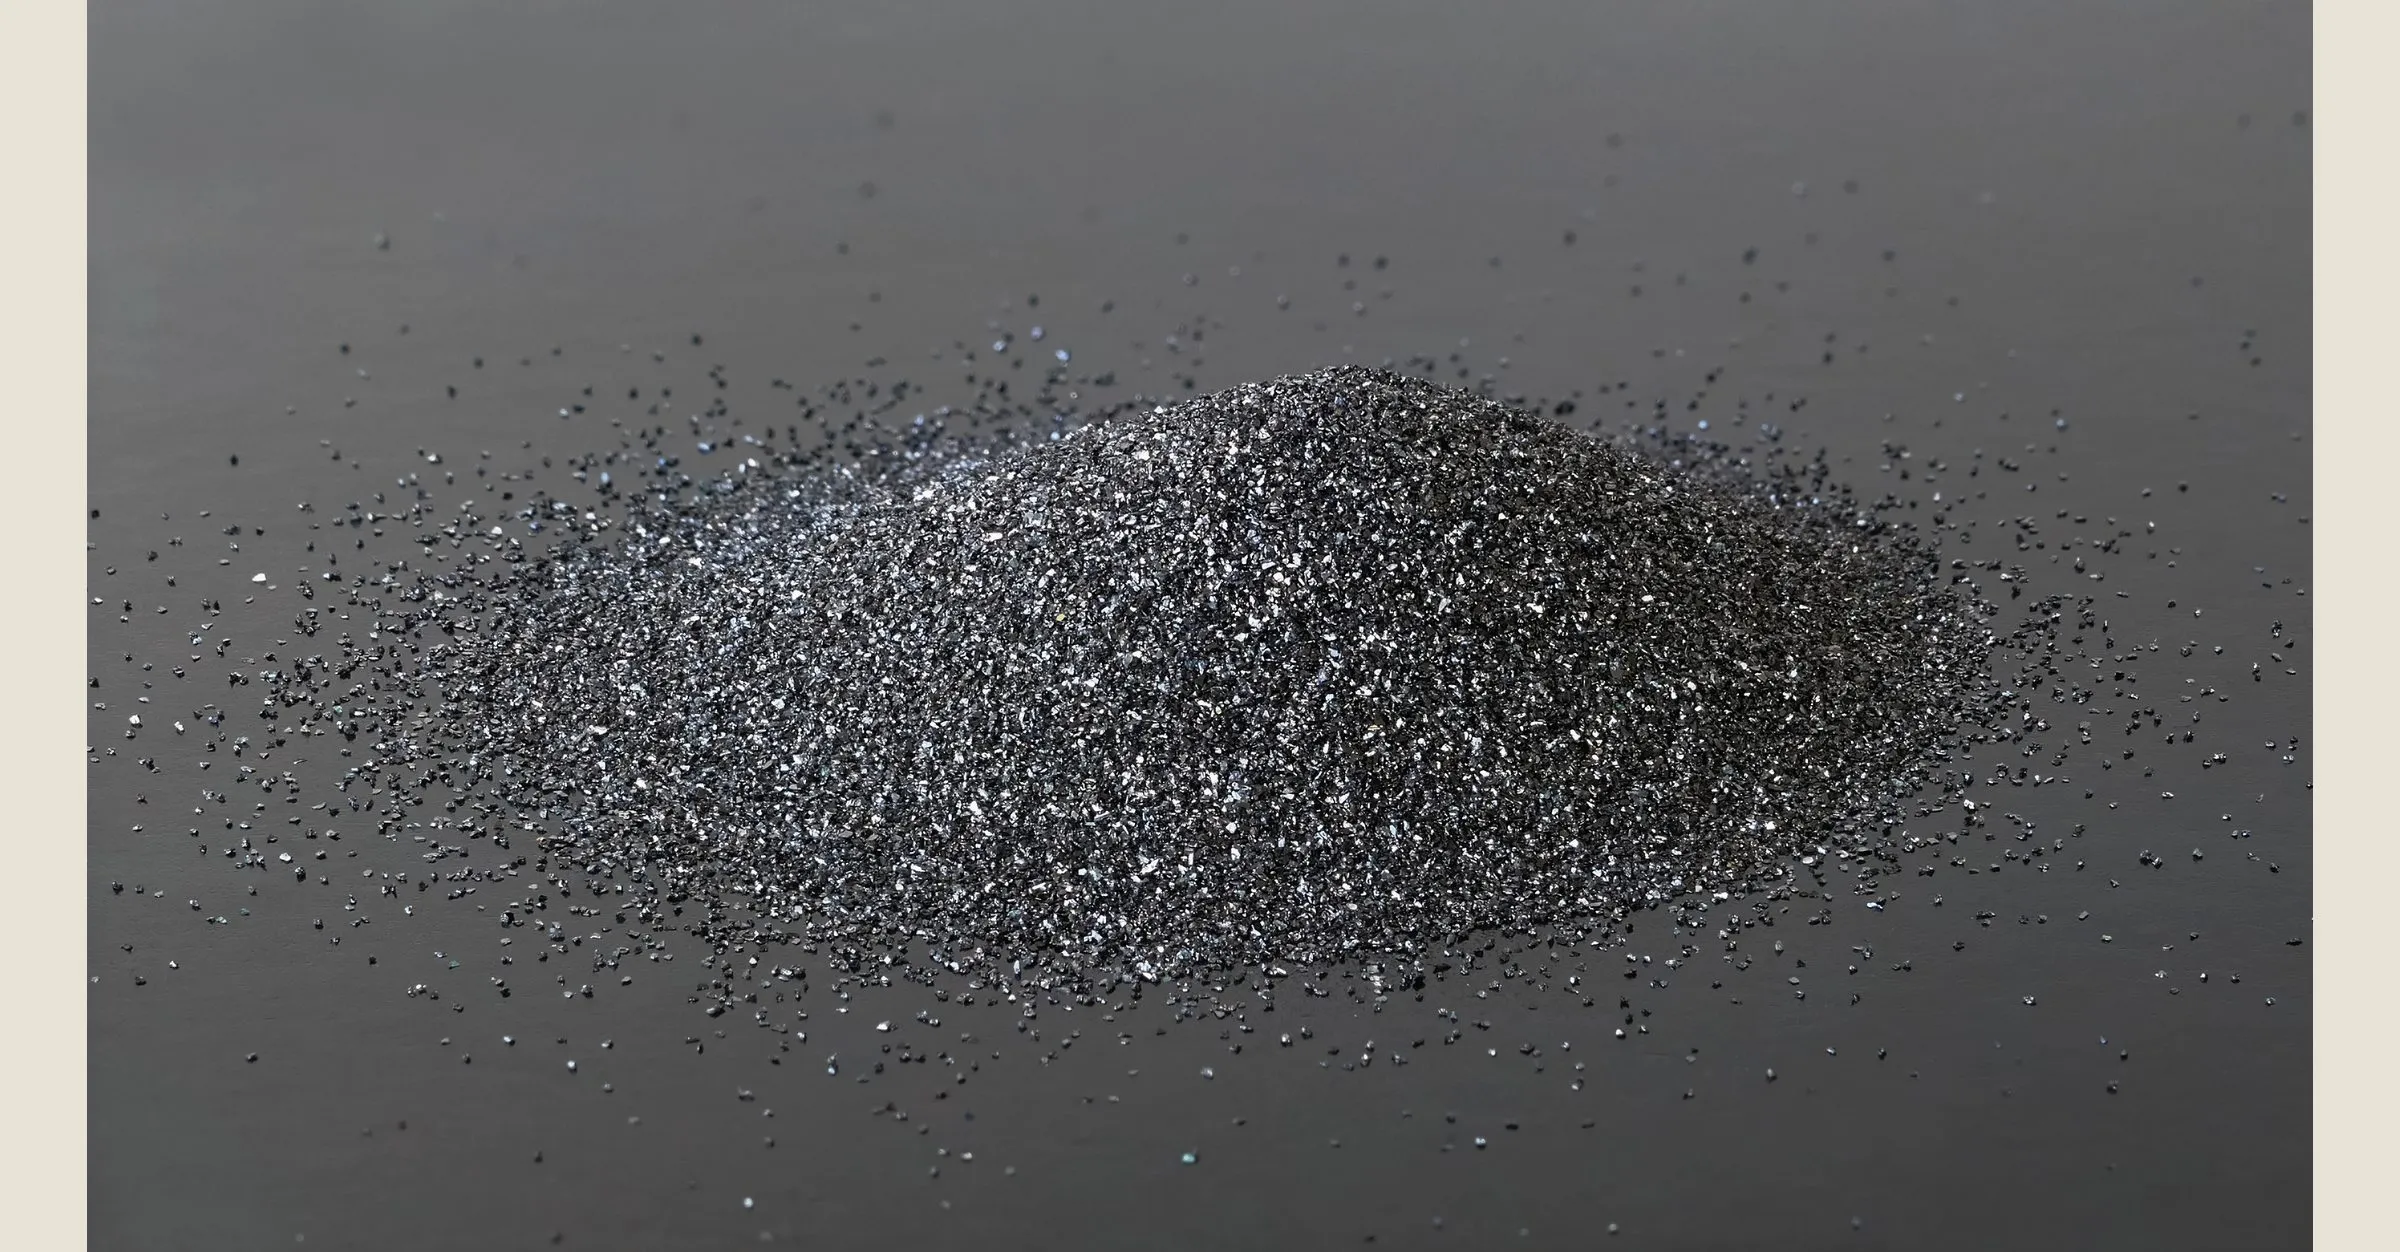
Silicon carbide manufacturers do not belong to one industry. One group makes abrasive and metallurgical grit and sells it by the tonne, at an average import value of $829 a tonne for crude material entering the United States in 2025. Another group grows single crystals and sells substrates by the wafer, at prices that appear in none of the sources used here, and that are quoted per piece after qualification. The two share a chemical formula and nothing else: no common plant, and no common price basis.
That is the first thing to establish before reading any silicon carbide manufacturers list, because a list that mixes grit producers with wafer suppliers invites a buyer to compare a commodity with a qualified component.
Ranking basis and date. Abrasive-grade figures come from the USGS Mineral Commodity Summaries 2026, reporting 2025 estimates. Substrate shares come from TrendForce, reported on 16 September 2025 for the 2024 market. Company roles come from the companies’ own announcements, dated where they are used. Data as of November 2026.
One name, two supply chains
| Abrasive and metallurgical grade | Semiconductor substrate grade | |
|---|---|---|
| What is sold | Crude lumps, then crushed and graded grain and powder | Single-crystal boules sliced into polished wafers, plus epitaxial layers |
| Made by | Acheson furnace, quartz and carbon at high temperature | Physical vapour transport crystal growth, then wafering |
| Unit of sale | Tonne | Wafer, by diameter and specification |
| Price basis | Import unit value, $829/t crude in 2025 | Not published; quoted after qualification |
| Who buys | Bonded and coated abrasives, refractories, steelmaking, blasting | Power device fabs, and thermal-management applications |
The USGS abrasives chapter supplies the tonnage side. The trends below come from it, plus the companies that name themselves.
Abrasive grade: country capacity, not company capacity
The United States produced crude silicon carbide at two plants operated by two companies, with an estimated value of about $25 million in 2025. Output was estimated at 30,000 tonnes for the year, down from 45,000 tonnes in 2023. Apparent consumption was 120,000 tonnes, and net import reliance was 74%.
The same chapter puts US production capacity at 40,000 tonnes for both 2024 and 2025, so the furnaces ran well below what they could make while imports covered three quarters of demand. The USGS attributes the pressure to cost: China was the world’s leading manufacturer of abrasive silicon carbide in 2025, and imports from China continued to challenge producers in the United States and Canada even with Section 301 duties on top of normal tariff rates.
Country capacity is published, and it answers a different question from the import table:
| Country | SiC capacity, 2025 estimate (t) |
|---|---|
| China | 450,000 |
| Norway | 80,000 |
| Japan | 60,000 |
| Mexico | 45,000 |
| United States | 40,000 |
| Brazil | 40,000 |
| Germany | 35,000 |
| Venezuela | 30,000 |
| France | 20,000 |
| India | 5,000 |
| Other countries | 200,000 |
| World total, rounded | 1,000,000 |
China holds 45% of that silicon carbide capacity and the United States 4%, which is a different picture from the 88% import share. The chapter gives cost as the reason Chinese material wins — production costs were lower — not an absence of capacity elsewhere.
I do not rank abrasive producers by company capacity, for a specific reason: none of these sources publishes plant-level capacity. The USGS reports country capacity, production, trade and values; the firms publish plant lists and product families. A company ranking assembled from those would be a ranking of press releases. What can be measured is the country and trade structure, and for a silicon carbide manufacturers list that is more informative than a ranking.
The import structure is the real map
For 2021–24, the USGS gives import sources by grade, and the split matters:
| Grade imported | China | Brazil | Canada | Norway | Other |
|---|---|---|---|---|---|
| Crude silicon carbide | 97% | — | — | — | 3% |
| Ground and refined silicon carbide | 61% | 14% | 10% | 8% | 7% |
| Total | 88% | 4% | — | — | 8% |
The distribution has a clear shape: China holds almost all of the crude trade and a bare majority of the finished grain trade, while Brazil, Canada and Norway appear only once the material has been milled and graded.
The chapter prices only the crude stage. The average unit value of imported crude silicon carbide was $587 a tonne in 2021, $1,080 in 2022, $905 in 2023, $832 in 2024 and an estimated $829 in 2025. That is a commodity curve: it rose 84% into 2022 and has drifted down since, which is what a furnace business running below its capacity looks like.
Two smaller facts belong in any sourcing conversation. About 5% of silicon carbide is recycled, according to the same chapter, and the tariff treatment differs by form: crude material enters under HTS 2849.20.1000 duty-free, while grain enters at 0.5% under 2849.20.2000 before any Section 301 addition.
Abrasive producers that name themselves
Three companies describe their own silicon carbide operations in enough detail to place them. Each entry is what the company says about itself, not an audited capacity.
Washington Mills (United States) entered silicon carbide in 1986 by acquiring the Carborundum electro-minerals business, and later acquired the Exolon Company, which brought plants in Hennepin, Illinois, Tonawanda, New York and Orkanger, Norway. Its homepage calls it the only North American producer of brown fused alumina, white fused alumina, silicon carbide and boron carbide crude ore, a claim that sits awkwardly beside the USGS count of two US producers of silicon carbide. The Acheson process its predecessor commercialised in 1890 is still the primary method, on the company’s account.
Fiven (Norway; part of Kymera International) lists silicon carbide under the SIKA brand across abrasive, refractory, metallurgical, technical ceramic and high-purity electronics grades, and its contact page lists a Brazil location under the names Fiven Brazil and Carbeto de Silício SIKA Brasil, in Minas Gerais. The listing does not state which grade is made where.
ESK-SIC (Frechen, Germany) presents silicon carbide as a raw material and sells into cutting, grinding and polishing media, high-temperature materials, functional fillers and semiconductor technology, offering analytics services and material development as separate services.
A fourth group matters for the trade numbers but cannot be profiled the same way: the Chinese furnace operators behind the 97% crude import share. None of them appears in a source used here with a verifiable product page in English.
Semiconductor substrates: the one place with shares
The substrate market is concentrated enough that a research firm publishes shares for it, and the numbers are unusually lopsided. TrendForce reported that in 2024 Wolfspeed led the global silicon carbide substrate market with 34%, while the Chinese suppliers TankeBlue and SICC each held 17%.
Three firms, 68% of the market. The TrendForce note gives no figure for the remaining 32% and does not state whether the share is measured on revenue or on wafer volume, so treat the number as a concentration measure rather than a capacity count. Two things it does establish: the leader is not Chinese, and the two challengers are.
That second point is the part to watch: TrendForce describes the two Chinese suppliers as catching up, and the same note says China is rapidly expanding six-inch capacity. A 2024 ranking can therefore be stale without being wrong.
Substrate suppliers, one by one
The three firms with published shares come first, then the suppliers that name themselves without a published share.
Wolfspeed (United States) held 34% of the substrate market in 2024 on the TrendForce figure, and launched its 200 mm materials portfolio commercially on 10 September 2025, with 200 mm bare wafers at 350 µm thickness and 200 mm epitaxy offered for qualification at the same time. The release describes doping and thickness uniformity as the gain from the larger diameter. Its boilerplate also refers to the company’s Chapter 11 proceedings, which a procurement reader should not skip: market leadership and financial distress are coexisting facts here.
TanKeBlue (Beijing) tied at 17% in the same 2024 ranking. Its own site lists 8-, 6- and 4-inch conductive substrates, 6- and 4-inch semi-insulating substrates, and 6- and 8-inch conductive epi-wafers, and lists substrate sites in Jiangsu and Shenzhen plus a crystal-growth furnace site in Shenyang, with a contact address in Beijing. It also records a multi-year wafer and ingot supply agreement with Infineon signed in May 2023.
SICC (Shandong, 688234.SH) held the other 17% in 2024 and now claims more: a March 2026 release on its own site says it ranked first globally in overall and in 6-inch and 8-inch silicon carbide substrate share for 2025, citing Fuji Keizai statistics. That is a company claim about a later year than the TrendForce figure, and the two are not directly comparable. Its catalogue covers 4H n-type, semi-insulating and p-type substrates.
Coherent (United States) sells semi-insulating substrates and epitaxy up to 200 mm, plus conductive substrates, and announced a 300 mm platform on 3 December 2025, built on its 200 mm experience, with datacenter thermal management as the primary target and power electronics and AR/VR also cited. The company says it plans to ramp the platform in high volumes; that is a plan, not output.
SK Siltron CSS (SK group, operations in the United States and Korea) makes only materials: ingots, substrates and epi-wafers at 150 mm and 200 mm. Its own site draws the line that matters for this page, saying it does not make devices and does not compete with its customers.
Resonac (Japan) supplies silicon carbide epi-wafers grown on single-crystal substrates and announced a joint development agreement with Soitec in September 2024 covering 200 mm bonded silicon carbide substrates. It also holds a multi-year silicon carbide materials supply agreement with Infineon, announced on 12 January 2023.
Two more data points belong to the market rather than to a company. TrendForce, citing IT Home, reports that a large silicon carbide wafer plant in Wuhan has started production, with a first phase targeting 360,000 six-inch wafers a year, and that the plant aims to supply 30% of China’s domestic output; that is a target quoted secondhand, not a shipment figure. The same note relays that Samsung is working on eight-inch silicon carbide power devices with no commercialisation timeline announced.
A device catalogue is not a substrate list
A common error in reading silicon carbide suppliers is to treat a power semiconductor portfolio as evidence of crystal growth. It is not. A company can sell SiC MOSFETs, modules and bare die while buying every wafer it processes.
The 34 / 17 / 17 split above describes substrate suppliers only; a module catalogue says nothing about where those wafers were grown. The distinction matters at the point of purchase. A substrate supplier is qualified on crystal defects, resistivity and wafer shape; a device maker is qualified on the part number’s ratings and reliability data. If a buyer needs silicon carbide material, the question is which entity grows the boule and which plant slices it, not which brand appears on the module.
This is also why installed-capacity comparisons fail here: a fab’s wafer starts are not the same as a materials supplier’s boules, and neither is the same as a furnace’s crude output.
How to read a silicon carbide suppliers list
The questions worth asking before an order are narrower than a brochure suggests, and each can be asked in writing.
- Which grade is being offered: abrasive grit, refractory grain, metallurgical addition, high-purity electronics grade, or semiconductor substrate? The grade determines everything downstream, and grit sold as “high purity silicon carbide” means something entirely different from an electronic-grade substrate.
- What is the unit and the basis: per tonne of graded grain, or per wafer of a stated diameter and thickness, with the diameter and the thickness both stated (Wolfspeed’s 200 mm material is 350 µm)? A quote that does not state the unit cannot be compared with any other quote.
- What is the defect specification: for substrates, micropipe density and dislocation density per square centimetre, measured by a named method. For grit, chemistry limits and particle-size distribution.
- Which plant produces it: a furnace, a milling and grading line and a wafer fab are three different addresses, and a product-family page proves none of them.
- What is the qualification status: a substrate in sampling is not a substrate in production, and a supplier’s own announcement of a launch is not a customer’s qualification.
For the financial and structural side of the alumina chain, the alumina manufacturers guide uses the same method on a different material. The rest of the supplier pages are collected under suppliers, and the material-level guides under industrial materials.
Methodology
This page uses one USGS commodity chapter for all silicon carbide tonnage, capacity, trade, price and duty figures (2025 estimates, published February 2026), one research firm’s market-share statement for substrate concentration (2024 shares, published September 2025), and company announcements and product pages for diameter, product, site and status claims, each dated where a date exists on the page cited.
Company logos in the two rosters are the marks each company publishes on its own site, resized and shown for identification only; no product photographs from press materials are reproduced. Two monochrome marks supplied only in white were recoloured to a dark neutral so they stay visible on a light background.
The two rosters are companies describing themselves. Where a company asserts a market position, it is labelled as a claim and kept separate from research data: SICC’s 2025 first-place statement rests on Fuji Keizai data, covers a later year than the 2024 TrendForce ranking, and reaches a different conclusion, so the two are reported side by side rather than merged. No company entry carries a capacity figure, because none of these sources publishes one at plant level.
The two sides are not combined. Tonnes are not converted into wafers, and shares are not converted into tonnes. Capacity and output are read together only for the United States, where the chapter publishes both; no utilisation rate is calculated for any other country. Capacity is quoted only at country level, which is the level the chapter publishes; no company-level capacity is stated anywhere on this page because none of these sources provides one, and no company ranking is inferred. Where a company’s statement about itself is used — Washington Mills’ North American position, Fiven’s product listing — it is presented as the company’s own wording. Where a figure is secondhand (the Wuhan plant target, Samsung’s timeline), the relay is stated. No global market-size forecast and no price forecast is inferred.
Sources
- USGS, Mineral Commodity Summaries 2026 — Abrasives (Manufactured), February 2026. https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-abrasives.pdf
- TrendForce, “Silicon Carbide Battle Rekindled by Industry Giants”, 16 September 2025. https://www.trendforce.com/news/2025/09/16/news-silicon-carbide-battle-rekindled-by-industry-giants-wolfspeed-samsung-make-waves/
- Wolfspeed, 200mm silicon carbide materials portfolio launch, 10 September 2025. https://investor.wolfspeed.com/news/news-details/2025/Wolfspeed-Announces-the-Commercial-Launch-of-200mm-Silicon-Carbide-Materials-Portfolio-Unlocking-the-Industrys-Ability-to-Manufacture-at-Scale/default.aspx
- Coherent, 300mm silicon carbide platform, 3 December 2025. https://www.coherent.com/news/press-releases/Coherent-expands-silicon-carbide-platform-with-300mm-capability-to-support-growing-demand-of-ai-and-datacenters
- Washington Mills, silicon carbide product page and company homepage (company claims). https://www.washingtonmills.com/silicon-carbide · https://www.washingtonmills.com/
- Fiven (Kymera International), SIKA silicon carbide product pages (company product listing). https://www.fiven.com/
- ESK-SIC GmbH, silicon carbide raw material and application pages (company site). https://esk-sic.com/home
- TanKeBlue Semiconductor, corporate and product pages (company site). https://en.tankeblue.com/
- SICC, corporate site including the 24 March 2026 market-share release (company claim). https://www.sicc.cc/en
- SK Siltron CSS, company and product pages (company site). https://www.sksiltroncss.com/
- Resonac, joint development agreement with Soitec on 200 mm bonded SiC substrates, 24 September 2024. https://www.resonac.com/news/2024/09/24/3292.html
- Resonac, multi-year SiC materials agreement with Infineon, 12 January 2023. https://eu.resonac.com/1201-23/